

Loan Services
Commercial Construction Loans
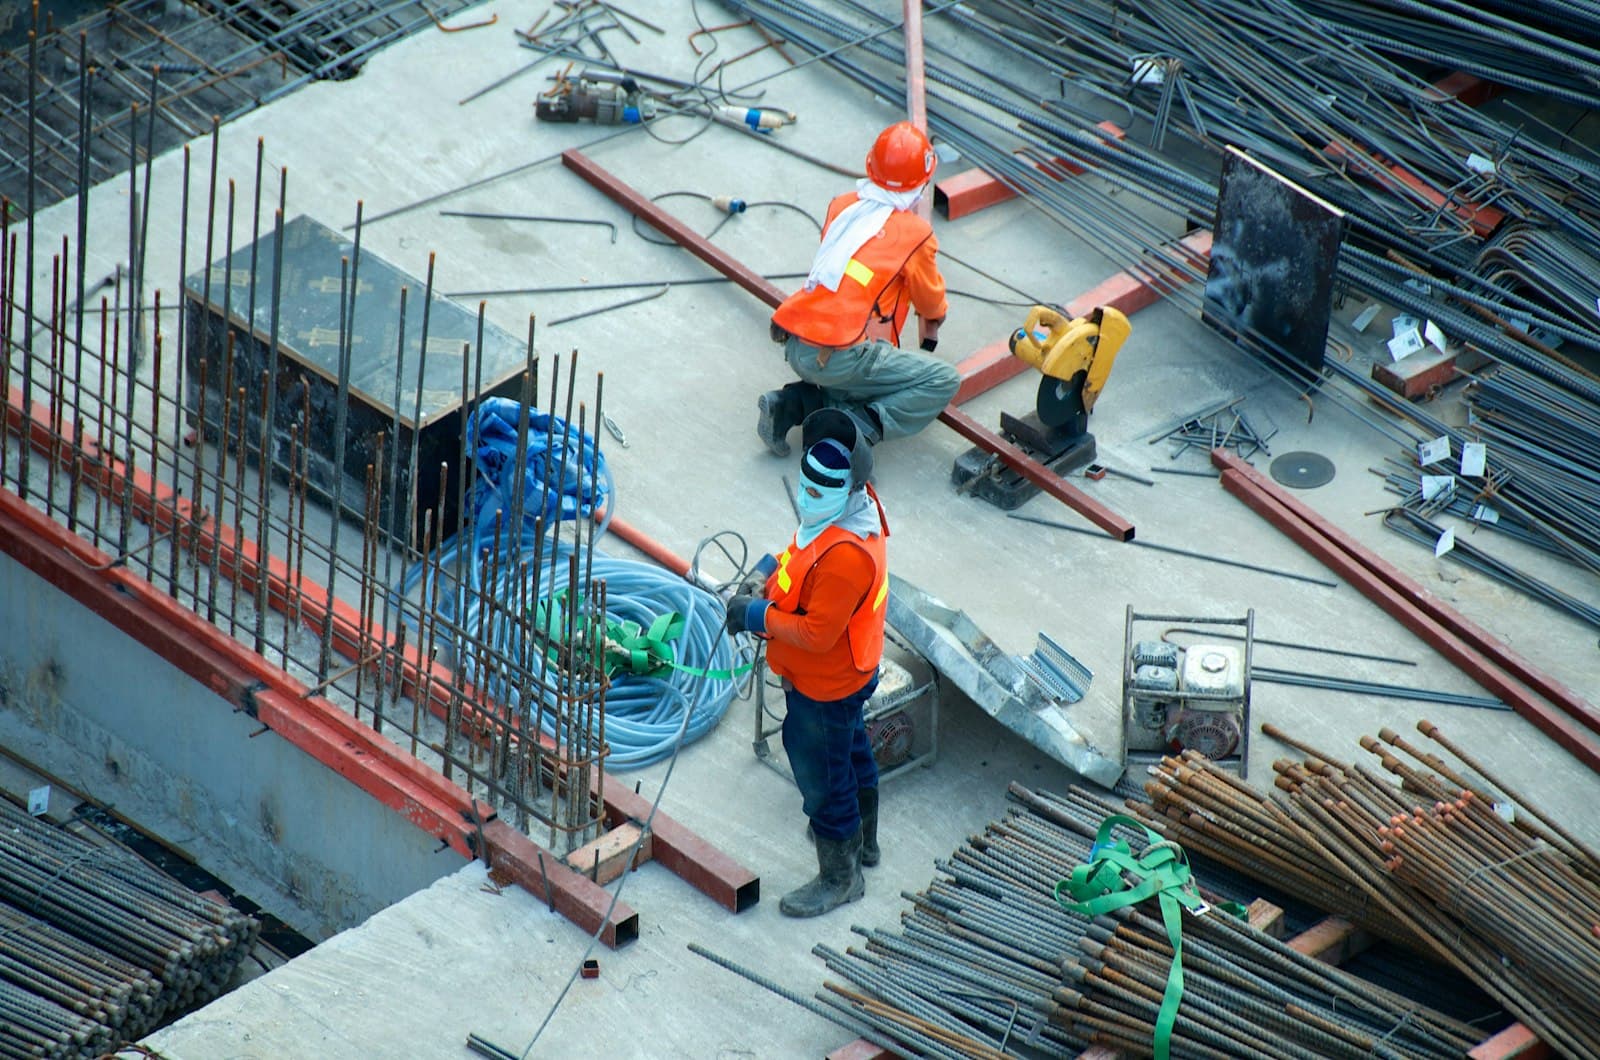
Phased, draw-based funding for ground-up builds and major renovations.
Is this you?
You're about to break ground and haven't lined up the draw schedule yet.
Your project needs a construction-to-permanent structure and you're not sure how that works.
You have seen a construction loan stall before over paperwork nobody warned you about.
If any of those sound familiar, or call +1 (305) 819-3675.
A Slipped Timeline Costs Tens of Thousands
Construction loans work fundamentally differently from a standard term loan: draws tied to milestones, interest-only payments during the build, and conversion to permanent financing at completion. A lender timeline that slips by weeks can cost a developer tens of thousands in carrying costs, expired permits and lost pre-leasing momentum.
60–120 days
Typical time to close a commercial construction loan
Why owners choose us for this
A fixed fee, quoted before we start.
You know the packaging cost before ground ever breaks.
The draw schedule is built before the first shovel.
We structure disbursements to your construction milestones and prepare the pro formas, contractor packages and budgets construction underwriters ask for, so funds arrive when the project actually needs them.
We handle the lender for you, start to close.
We manage lender communication and documentation requests through underwriting and closing, so a request doesn't sit unanswered while your crew waits.
5.0 · 555 Google reviews of SMAART Company
What you actually get
A draw schedule and lender package built before the first shovel.
Ready when you are
How it works
- 1
Assess
We review project scope, budget, timeline and your financial capacity to determine the right loan structure and lender fit.
- 2
Package
We assemble the complete construction loan package: pro formas, contractor bids, project plans and your financial statements.
- 3
Submit
We present the package to construction lenders active in your market and property type.
- 4
Underwrite
We manage lender communications, appraisal coordination and documentation requests through underwriting.
- 5
Fund
We close the loan and establish the draw schedule so disbursements flow as each milestone is completed.
Included Services & Outcomes
Keep exploring
Related loan services
Resources
Commercial Construction Loans insights
Questions
Commercial Construction Loans FAQ
How does a construction loan differ from a standard business loan?
Construction loans disburse in phases, called draws, tied to project milestones rather than as a lump sum. They carry interest-only payments during construction, require detailed project documentation, and typically convert to permanent financing at completion.
What documentation do construction lenders require?
Expect detailed project budgets, construction timelines, contractor qualifications and licenses, architectural plans, pro forma projections showing stabilized income, personal financial statements, and often a market feasibility study.
What is a construction-to-permanent loan?
It combines the construction phase and the long-term mortgage into a single closing, saving on closing costs, eliminating refinancing risk at completion, and locking your permanent rate before construction begins.
How long does it take to close a commercial construction loan?
Commercial construction loans typically take 60 to 120 days to close, given the complexity of documentation, appraisal requirements and feasibility review. Preparing a lender-ready package from the start meaningfully shortens that window.
What happens if my project runs over budget mid-construction?
This is exactly why an interest reserve and a realistic contingency are built into the loan structure upfront. If costs still exceed the reserve, we help you document the change order and go back to the lender before the shortfall stalls a draw.
Put SMAART Loans behind your commercial construction loans
Book a free consultation. We'll review your financing need, quote a fixed fee, and show you exactly which loan programs fit your business.